We thought such a project would take months. In just a few days, Koncile was live, automating our insurance certificate extraction and strengthening compliance across sites.
 Mike OskarsonCFO at, Mark Young Construction
Founded in 1989 in Frederick, Colorado, Mark Young Construction is a general contractor focused on commercial construction. It works on retail, grocery and school projects across the western United States. Like any general contractor, it never builds alone: every job site brings in a chain of subcontractors, plumbers, electricians, framers, whose presence on site depends on one specific piece of paperwork, the certificate of insurance. Managing that seemingly minor document ended up taking up a disproportionate share of Mark Young's administrative team's time, until they automated its reading with Koncile's data extraction platform.
The certificate of insurance, a mandatory step before every job
Before a subcontractor can start work, the general contractor has to confirm they carry adequate insurance coverage, general liability and, depending on the trade, sometimes auto or workers’ compensation, and that the general contractor itself is named as an additional insured on that policy. That check runs through a standardized document, the certificate of insurance (COI), which the subcontractor sends over before work begins. At Mark Young, that check was done by hand: reading the document, re-entering the relevant fields (insurer, policy number, effective and expiration dates, coverage limits), then tracking deadlines in an internal spreadsheet. The process worked, but it cost time with every new subcontractor, left room for missed expiration dates, and made audits slower to prepare without a centralized, consistent record.
Why a certificate of insurance is harder to read than it looks
A certificate of insurance fits on a single page, but it packs in several distinct coverage lines (general liability, auto, umbrella, workers’ compensation), each with its own insurer, policy number, effective and expiration dates, and limits. Most U.S. certificates follow a standard form, ACORD 25, whose dense layout leaves little room for ambiguity, except on a few fields. One of them shows the difficulty well: the “Gen’l Aggregate Limit Applies Per” line offers three checkboxes, Policy, Project and Location, which determine whether the aggregate coverage limit applies per policy or per job site. A box checked under “Project” rather than “Policy” concretely changes the level of coverage actually available for a given job, a distinction that has long required a careful, almost legal reading of every certificate.
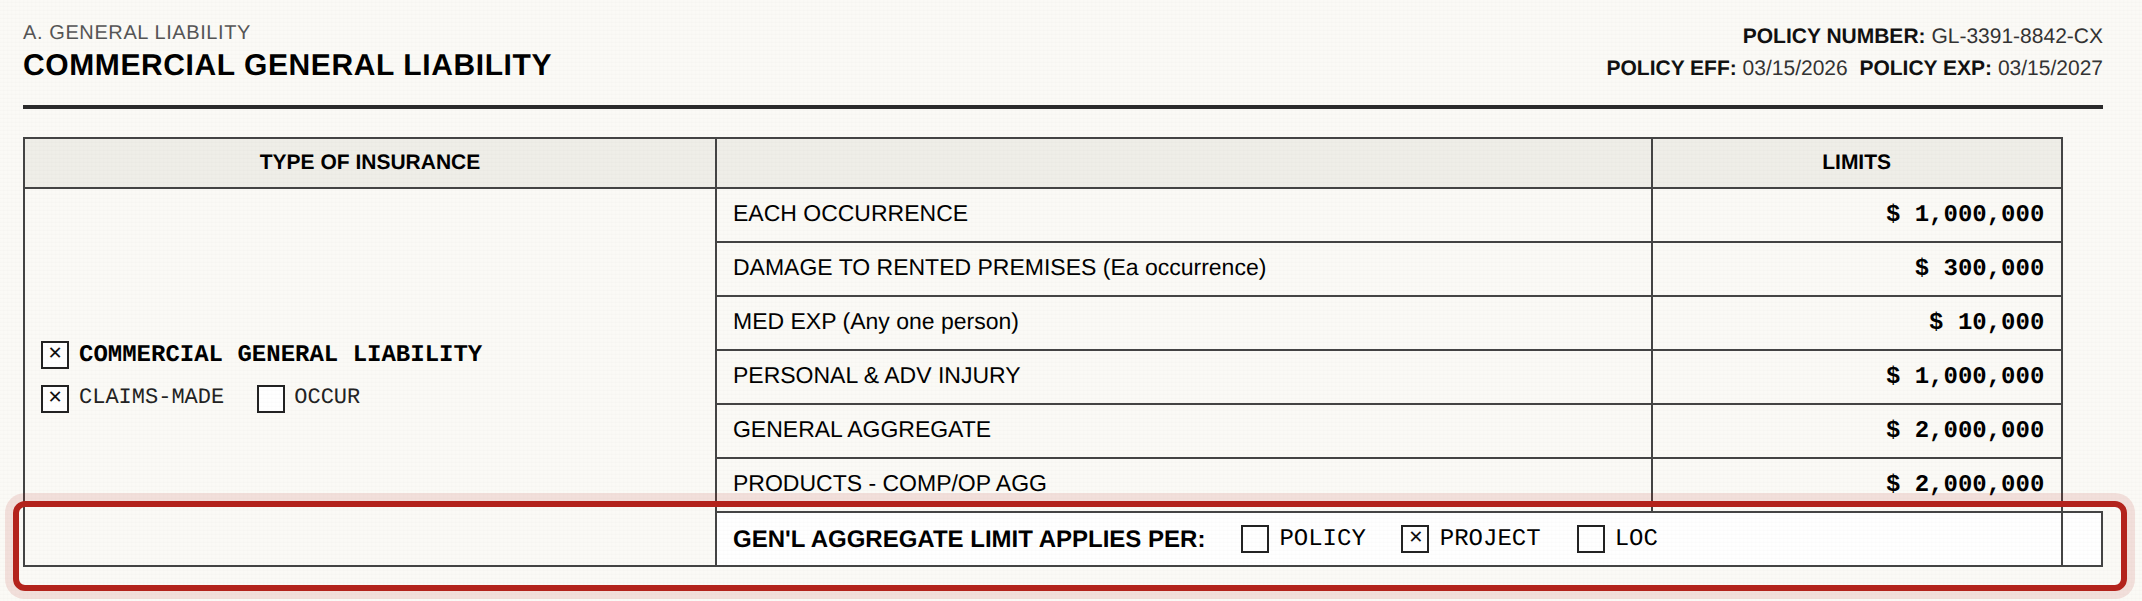
This is exactly the field Mark Young’s team reached out to Koncile about, asking for the extraction to be configured to reliably capture which box was checked, using a real certificate from one of its subcontractors. That concrete case illustrates well what makes these documents hard to automate: it isn’t enough to spot a keyword, the system has to interpret a checkbox in context, understand the form’s structure, and tell a meaningful field apart from one left blank by mistake.
Automated extraction, configured around Mark Young’s own compliance rules
Koncile relies on its OCR API and its data extraction engine to read every certificate of insurance and return its key fields: insurer, policy numbers, coverage types, effective and expiration dates, limits, additional insured status. That automated reading works regardless of the format the document arrives in (native PDF, scan, photo), which matters for an inbound flow that depends on how each subcontractor happens to send their certificate. Rather than a generic model, the extraction was set up with custom fields modeled on Mark Young’s own compliance rules, including that “General Liability Project Applies” field. This tailored extraction logic runs on the same building blocks as Koncile’s OCR and document extraction, used well beyond certificates of insurance to structure a wide range of document types across other industries, including the insurance sector.
Who does what between Koncile and Mark Young Construction
This comparative table highlights the division of roles between Mark Young Construction and the Koncile platform in managing insurance certificates. It illustrates how the company's decision-making process seamlessly integrates with the platform's automated data extraction.
A certificate backlog cleared, and ongoing tracking that became a non-issue
After several months of use, the main result for Mark Young isn’t a headline number but a change in the nature of the work itself: the workload that certificate verification used to represent, once constant, became residual. The backlog of certificates that needed updating got thoroughly worked through, and the ongoing tracking that remains, for a company that keeps working with existing and new subcontractors alike, now takes only a limited amount of time.
The AI works as I would expect and was very helpful in our transitioning to a new way of capturing COI’s. We have now fully transitioned and the little time it takes to make changes is not very cumbersome.
Mike Oskarson, CFO, Mark Young Construction
Collected several months after the rollout, this feedback sums up the project well: a full transition to a new way of capturing certificates, with a maintenance effort that, by the client’s own account, stays manageable once the process settles into a routine.
What’s next: a check that never really stops
For a general contractor, checking certificates of insurance never really stops: it starts over with every new subcontractor and every policy renewal. The same exercise, on equally dense documents, comes up in other corners of insurance too, for instance when checking underwriting files at Toyota Insurances.